Illinois Transfer on Death Instrument (Entity Beneficiary)
County Specific Legal Forms Validated as recently as October 24, 2026 by our Forms Development Team
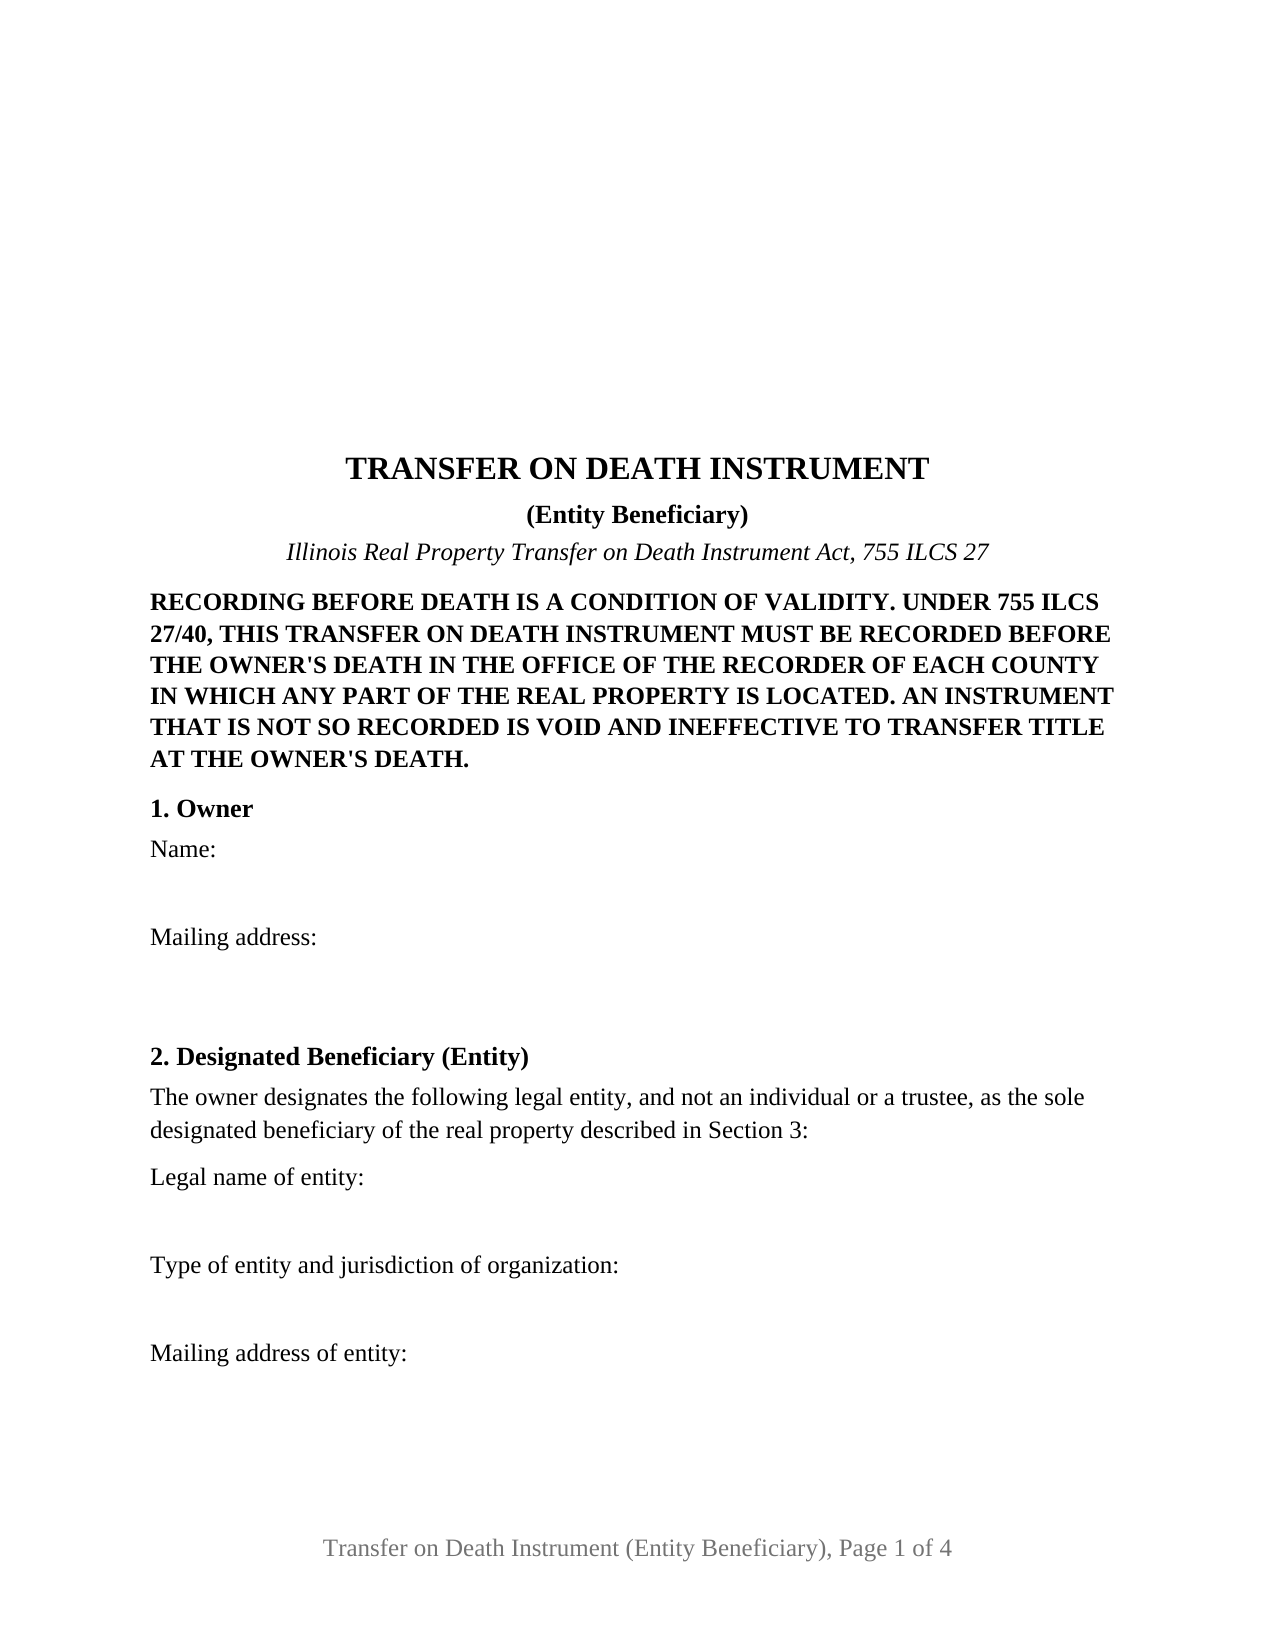
About the Illinois Transfer on Death Instrument (Entity Beneficiary)
How to Use This Form
- Select your county from the list
- Download the county-specific form
- Fill in the required information
- Have the document notarized if required
- Record with your county recorder's office
What Others Like You Are Saying
"THESE FORMS ARE JUST WHAT I NEEDED, SHORT AND TO THE POINT. EXCELLENT QUESTIONS FOR MY NEED. THAK YO…"
"Wonderful forms, been coming here for years (since 2012) for my deed forms and they have never faile…"
"Everything was straight forward. I think I was able to accomplish my objective."
"I am very pleased with Deeds.com. They responded back very quickly, checked my forms, gave an exampl…"
"I was very happy with this site. It included all the papers I needed, instructions, and even an exam…"
4.8/5 from 4,833 reviews. Read all
An Illinois owner can leave real estate to an organization the same way a transfer on death instrument leaves it to a person: by naming the organization as the designated beneficiary and recording the instrument during life. This form prepares that configuration under 755 ILCS 27, the Illinois Real Property Transfer on Death Instrument Act. A single owner names one legal entity, a corporation, not-for-profit corporation, limited liability company, partnership, association, or unit of government, to take Illinois real property at the owner's death without probate.
An organization as the beneficiary
Section 5 of the Act defines the person who may be a beneficiary to include a corporation, a partnership, a limited liability company, an association, a governmental subdivision, or any other legal entity. A house left to a church, a farm left to a conservation foundation, a rental building left to the family limited liability company that manages it: each is a transfer on death deed, as other states call it, with an entity on the receiving end. The form identifies the entity by exact legal name, type and jurisdiction of organization, and mailing address; its fixed recital states that the beneficiary is a legal entity and not an individual or a trustee.
If the entity no longer exists
An entity does not die, but it can dissolve, and the Act answers that case where it answers a predeceased individual. Section 65(a)(3) provides that where the owner has identified a single designated beneficiary and that beneficiary fails to survive the owner or is not in existence on the date of the owner's death, the real property passes to the owner's estate. The form names one entity and carries no alternate, so that rule applies as written; the Act is silent on a later merger or name change, and the instrument identifies the entity as named and organized on the day it is signed.
No transfer declaration for a gift to a charity
An Illinois recorder may not accept a deed without transfer tax stamps and a PTAX-203 declaration unless an exemption in 35 ILCS 200/31-45 applies. A transfer on death instrument is given for no consideration, which places it under paragraph (e), the exemption for a deed where the actual consideration is less than $100, and under 86 Ill. Adm. Code 120.5 a paragraph (e) transfer is noted on the face of the document with no declaration. Paragraph (b)(3) separately exempts property acquired by a charitable, religious, or educational organization, and the Department of Revenue's PTAX-203 instructions direct that paragraph (e) be selected where both apply. The form prints the paragraph (e) notation in its own numbered section.
Signed before two witnesses, acknowledged once
Under Section 45 of the Act the owner signs, two or more credible witnesses attest in writing to the signing, the owner's free and voluntary act, and the owner's sound mind and memory, and the signatures of the owner and the witnesses are acknowledged before a notary public; fewer than two credible witnesses leaves the instrument void. The form prints the attestation above two witness blocks and carries one acknowledgment certificate naming the owner and both witnesses, a layout rather than a rule of Illinois law. Section 40 makes recording before the owner's death, with the recorder of each county where the property lies, a condition of validity, stated in capitals under the form's title.
What this configuration recites
The form recites exactly one owner, an individual who signs personally, with no marital status recited, and exactly one designated beneficiary, a legal entity, with no second beneficiary, shares, or successor clause. A sole owner leaving a residence to a not-for-profit corporation, a widowed owner leaving farmland to a park district, and an owner leaving a rental property to a limited liability company present the pattern this instrument recites. An individual or trustee beneficiary, two or more beneficiaries, two owners on one instrument, and a spouse's waiver of the Section 66 renunciation right present configurations this form is not set up as. Under Section 60 the owner may still sell, mortgage, or lease the property during life, and the entity holds no interest until death.
The package contains the fillable instrument, a completed example built on a McLean County fact pattern in which the owner names an Illinois not-for-profit corporation, and the guide covering each section, the witness and notary formalities, and recording. The guide and this description describe the form and the statutes it rests on in general terms; neither is legal advice.
Important: County-Specific Forms
Our transfer on death instrument (entity beneficiary) forms are specifically formatted for each of the 102 counties in Illinois.
After selecting your county, you'll receive forms that meet all local recording requirements, ensuring your documents will be accepted without delays or rejection fees.